 By
The Reserve Bank of Zimbabwe (RBZ) is currently engaged in advanced discussions to adopt India’s acclaimed Unified Payments Interface (UPI) framework to serve as the core of a unified national digital transactions system.
The proposed technology transfer promises to streamline electronic payments across the country, enabling consumers to execute instant, cross-platform money transfers and make merchant payments using a single QR code.
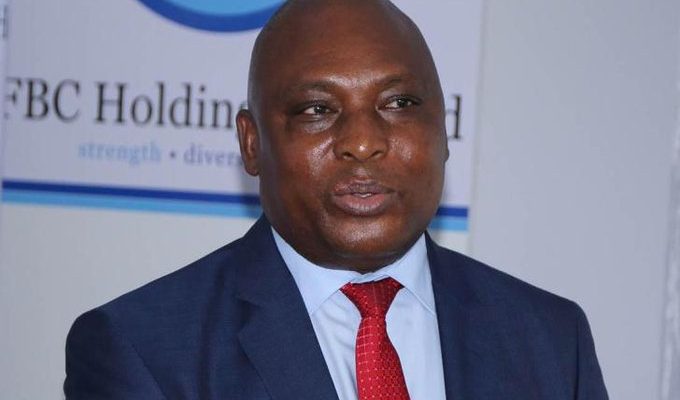
The monetary authority is negotiating with NPC International Payments Limited (NIPL), the global arm of the National Payments Corporation of India, to construct the foundation of Zimbabwe’s National Payments Digital Public Infrastructure. Reserve Bank Governor Dr. John Mushayavanhu confirmed the ongoing talks, noting that while a formal pact remains pending, October 31 has been targeted as the milestone for concluding discussions.
“Despite technological advances, payments remain slow, fragmented and costly,” Dr. Mushayavanhu noted during an interview.
“The proposed platform will complement, not replace, the country’s existing payment infrastructure. It will provide common payment rails through which banks, mobile money operators, payment service providers, fintechs and other regulated participants can connect and transact in real-time. Thus, improving the affordability of digital payments is one of the principal objectives of the initiative.”
Under the envisaged architecture, retail customers will no longer be restricted by separate banking or mobile wallet systems. A shopper could make purchases at participating merchants by scanning a single universal QR code via any supported bank account or digital wallet app.
Likewise, peer-to-peer transfers between distinct financial entities would occur seamlessly on real-time rails, bypassing legacy inter-platform hurdles.
This integration promises major operational relief for small and informal businesses, which currently juggle multiple point-of-sale setups and disparate payment channels to accommodate customers. Under the unified setup, micro-merchants can display a single display QR code to accept payments across all participating services.
Dr. Mushayavanhu likened the initiative to vital civic utilities, framing the network as a fundamental foundation for economic activity.
“The intended outcome is a Zimbabwean national payments ecosystem that would be deployed and operated as a domestic instant payments public infrastructure, much like roads, dams and power grids,” he explained.
Eliminating duplicated network connections and reducing intermediary operational friction across financial service providers is central to the project’s design.
While Dr. Mushayavanhu reiterated that “improving the affordability of digital payments is one of the principal objectives of the initiative,” he tempered immediate expectations regarding fee structures.
“It would be premature to guarantee a particular reduction in customer charges before the system rollout,” he cautioned.
Beyond cost efficiency, the framework introduces streamlined user identifiers allowing transactions via basic handles such as phone numbers, emails, or digital payment IDs instead of lengthy bank account details.
Central bank officials emphasize that the platform will work alongside existing QR-code standards, establishing common underlying routing to enhance financial inclusion and unlock innovation for domestic fintech companies.

Comments