 By
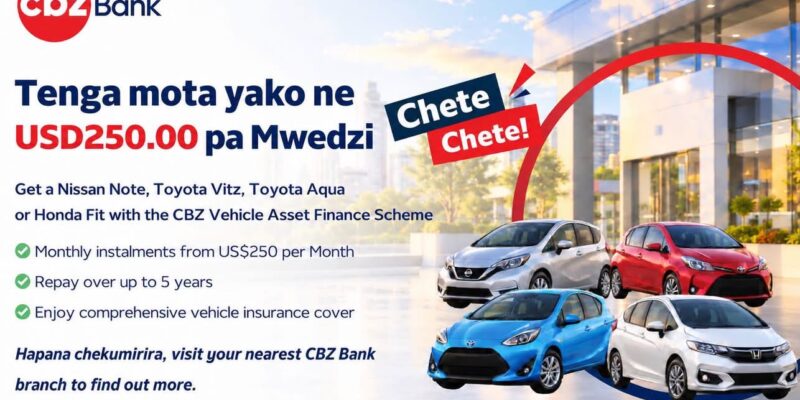
CBZ Bank has rolled out a Vehicle Asset Finance promotion designed to help Zimbabwean motorists acquire personal cars through monthly repayments starting from USD$250 over periods of up to five years.
The offer covers both local purchases and imported vehicles, such as popular compact models like the Nissan Note, Toyota Vitz, Toyota Aqua, and Honda Fit.
For buyers short on cash, driving off with immediate transport while spreading payments over 60 months sounds like an ideal solution. However, financial details reveal that the total cost over five years goes well beyond the headline figure.
At a headline rate of USD$250 per month over 60 months, a borrower pays USD$15,000 in loan installments. But paying USD$15,000 in monthly installments does not mean you are buying a USD$15,000 car outright.
In asset financing, the total expenditure typically involves an initial deposit, interest charges, bank administrative fees, and required insurance.
For example, on a USD15,000 vehicle setup requiring a standard 25% deposit (USD3,750), the financed loan balance would sit at USD$11,250.
Assuming an illustrative nominal interest rate of 18% per annum on a reducing balance:
• Monthly Loan Installment: USD$285.68
• Total Loan Installments (60 months): USD$17,140.56
• Deposit + Total Installments: USD$20,890.56
Before adding extra bank charges or vehicle insurance, the total payment already exceeds the original price tag by almost US$5,900.
A complete breakdown must account for standard financing fees:
• Establishment Fees: Often calculated at 3% of the loan amount (around USD$337.50 on an $11,250 balance).
• Comprehensive Motor Insurance: Typically around 4.5% of the vehicle value annually (approx. USD$675 per year through providers like CBZ Insurance).
• Credit Life Insurance: Often set around 1% of the vehicle value (approx. USD$150).
When added together, these fees can push the ultimate cost above USD$22,000 for a USD$15,000 car.
Conversely, if a buyer’s budget strictly caps repayments at USD$250 per month under similar interest assumptions, the maximum loan supported over 5 years is roughly USd$9,849. To buy a vehicle valued around USD$13,132, the buyer must pay a USD$3,283 deposit upfront, bringing total payments (deposit plus 60 monthly installments) to USD$18,283.
Many drivers compare financing to importing used Japanese models directly.
An imported vehicle listed overseas at USD$4,000 usually requires USD$1,200 for freight and USD$100 for insurance, reaching a CIF value of USD$5,300 before arrival.
After adding ZIMRA customs duties (roughly 40%) and VAT (15%), estimated customs taxes exceed US$3,200, landing the final cost around US8,500.
While direct importing requires less total cash, it demands 100% upfront capital and leaves the buyer waiting weeks for shipping and customs clearance. Vehicle financing trades higher overall cost for immediate access to transport and low upfront friction.
Before signing any vehicle asset agreement, buyers should request a full written disclosure and ask:
1. What is the required deposit percentage?
2. What is the exact annual interest rate and calculation method?
3. What are the establishment, monthly service, and compulsory insurance fees?
4. What happens in the event of early settlement or missed repayments?
CBZ’s scheme offers practical relief for motorists needing immediate mobility, but understanding the final repayment total ensures buyers choose a plan that fits their long-term budget.



Comments