 By
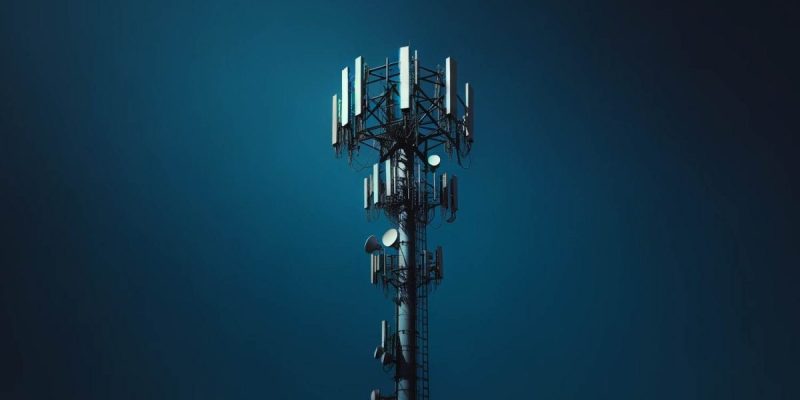
Mobile operators in Africa are facing severe economic and structural headwinds, holding roughly a quarter less radio spectrum than their international peers while paying significantly higher prices, according to the Spectrum Policy in Africa report published this month by GSMA Intelligence.
African network operators held an average of 570MHz of mobile spectrum below 7GHz at the end of 2025, compared to 750MHz in the rest of the world. Adjusted for total volume held, African carriers spend 0.82% of their revenue per 100MHz, compared to 0.66% globally.
Stringent licensing rules compound these expenses.
In Benin, direct spectrum costs eat up 7% of operator revenue, while attached coverage and quality-of-service obligations push effective costs up by an additional 66%. Meanwhile, average revenue per user (ARPU) across Africa has plummeted nearly 50% in real terms over the past decade, with revenue per megahertz per connection dropping over 69%.
Despite 4G coverage reaching 83% of Africa’s population and 5G covering 15%, device usage lags severely and only 28% of individuals access mobile internet on their own devices, compared to 66% globally. To bridge this gap, the GSMA advocates for lower auction reserve prices, 20-year technology-neutral licences, published spectrum roadmaps, and predictable renewals.
It estimates these reforms could expand 5G coverage to 170 million more people and add over $120 billion to Africa’s GDP between 2026 and 2035. Highlighting Rwanda’s turn away from a single wholesale network model where opening 800MHz and 2.6GHz bands in 2022 drove 4G usage from 2% to over 30% within two years, the report underscores the power of market-based spectrum allocation.
In Zimbabwe, local operators including Econet Wireless, NetOne, and Telecel, face operational realities that reflect many of these continental pressures. Monitored by the Postal and Telecommunications Regulatory Authority of Zimbabwe (POTRAZ), local players navigate high regulatory fees, multi-currency instability, and infrastructure import costs, which strain capital expenditure for network expansion.
While major operators have deployed 5G across urban hubs such as Harare and Bulawayo, nationwide rollout remains restricted due to spectrum availability in key capacity bands (such as 3.5GHz) and high deployment overheads.
The entry of alternative technologies, most notably the official licensing of satellite provider Starlink has added competitive pressure to terrestrial operators, highlighting the urgent need for competitive spectrum pricing, clear policy roadmaps, and policy modernization to encourage long-term digital investment.

Comments